Lee Restructuring Advisors
Financial advisory for Subchapter V and Chapter 11 debtors.
Cash flow forecasts, monthly operating reports, cash collateral budgets, and plan projections that the U.S. Trustee, the Subchapter V trustee, and the lender can trace line by line. Prepared by a former AlixPartners restructuring professional, working directly with debtor's counsel.
What we prepare
Every engagement is defined by deliverables, not hours. These are the documents a case runs on, and the point in the case where each one is needed.
| Deliverable | Used for | When |
|---|---|---|
| 13-week cash flow forecast | First-day and cash collateral motions, DIP budgets, weekly variance reporting | Petition week, then weekly |
| Monthly operating report | Reporting under §308 and Rule 2015(a)(6) on Form 425C, or UST Form 11-MOR outside the small business track | Every month of the case |
| Cash collateral and DIP budgets | Motions and orders under §363 and §364, lender consent, budget compliance reporting | First weeks, then per order |
| Plan projections and feasibility | Confirmation under §1129(a)(11) and §1191, disposable income under §1191(d), the best-interests test under §1129(a)(7) | Plan filing and confirmation |
| Lender, trustee, and committee reporting | Periodic reporting required by orders, Subchapter V trustee monitoring, committee information requests | As ordered |
| Retention paperwork | Application under §327 or §328, disclosure under Rule 2014, engagement letter, proposed order | At engagement |
Debtor's counsel
The most common starting point. Counsel needs numbers the U.S. Trustee and the trustee will accept, produced on the case calendar, without teaching the debtor's bookkeeper what a monthly operating report is.
Subchapter V trustees
When a debtor cannot produce reliable reports or a plan that holds together, the trustee is the first to see it. We work from the trustee's reporting expectations and the plan's feasibility test, not against them.
Owners and boards
A company in Chapter 11 needs a finance function that can close the month, forecast thirteen weeks, and explain a variance. If that function does not exist inside the company, we stand it up for the life of the case.
How an engagement is structured
Retained under §327 as the debtor's financial advisor
Counsel files the application; we supply the declaration under Rule 2014, the engagement letter, and the proposed order. Compensation is reviewed by the court under §330 or fixed under §328. This is the usual path when the work spans the case.
Engaged in the ordinary course within the budget
For a narrow scope, such as a single 13-week forecast or a set of plan projections, the work can run inside the approved budget where the court's orders and local practice allow. Which path applies is counsel's call. We prepare the paperwork either way.
Scope is fixed in writing before work begins. The person you speak with is the person who does the work. There is no team to be handed off to.
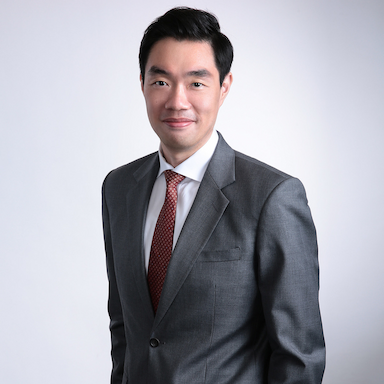
Principal
Juwon Lee
Former restructuring Vice President at AlixPartners. CFO of The Princeton Review through a $27M turnaround and an approximately $300M exit. Jefferies investment banking, with more than $4B in transactions. MBA, Kellogg School of Management. Based in Stamford, Connecticut; engagements nationwide.
Insights
MOR Requirements by District: Chapter 11 Filing Guide
Chapter 11 MORs are due by the 21st by default, but local-rule due dates, supplemental documents, and how courts modify reporting vary by district.
AR Factoring as DIP Financing in Subchapter V Chapter 11 Cases
Subchapter V debtors can use accounts receivable factoring as post-petition financing when the motion discloses the advance rate, the fee structure, the reserve, and the termination terms, and when the arrangement is reconciled to the 13-week forecast and the monthly operating report.
Subchapter V Confirmation Hearing Checklist: Financial Documents to Prepare
The financial exhibits a Subchapter V confirmation hearing turns on: the 13-week cash flow, profitability schedules, liquidation analysis, projected-versus-actual revenue, the individual debtor's personal financial statement, and proof of post-confirmation working capital.
Building Exhibit B Projections That Survive Subchapter V Confirmation
Plan projections for a Subchapter V case must show realistic revenue, conservative expenses, and cash flow that funds every payment the plan promises. What the feasibility test asks, the three assumption categories that get scrutinized, and the documentation failures that draw objections.
Official Form 425C: A Working Guide to the Subchapter V Monthly Operating Report
Form 425C instructions for Subchapter V and small business debtors: what each of the form's eight parts and 42 lines asks for, the Rule 2015(a)(6) deadline, the six exhibits, and where reports go wrong.
Discuss a case
Send the case posture and what is due next. You will hear back from Juwon Lee directly. Inquiries are held in confidence.